Muthaleetu Thisai · முதலீட்டு திசை
Mutual Fund · G Sangeetha · 17 Nov 2026
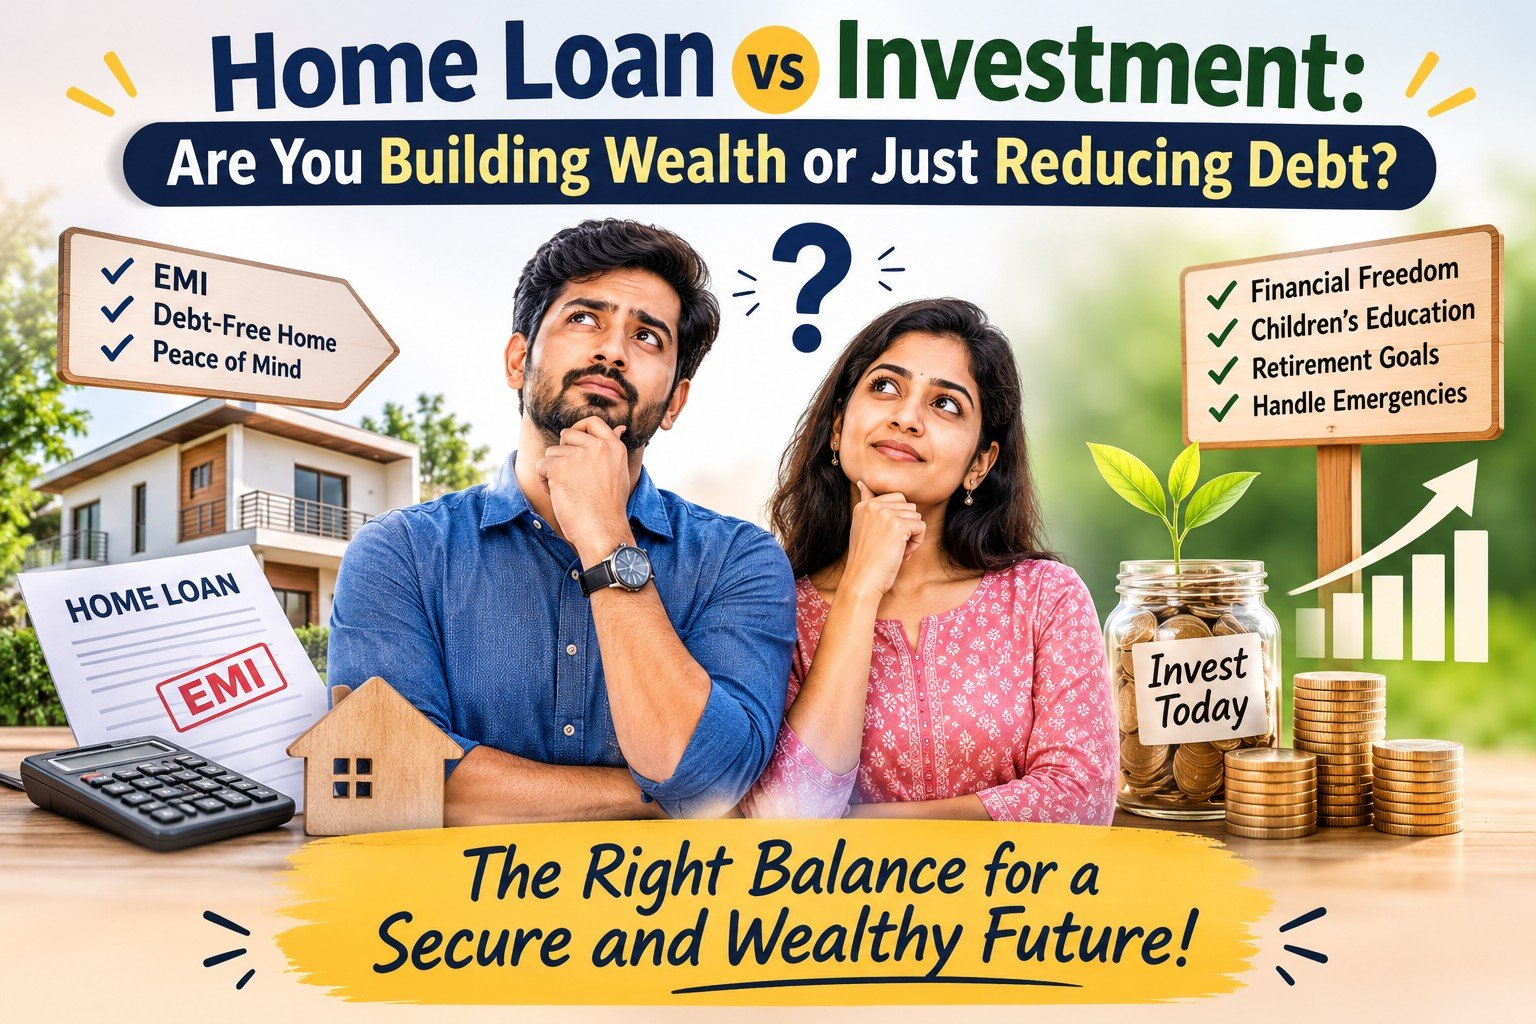
Home Loan vs Investment: Are You Building Wealth or Just Reducing Debt?
Buying a home is a lifelong dream for many families. Naturally, becoming debt-free becomes a priority. But while focusing on closing your home loan, are you giving equal importance to building your future wealth? Let's look at why this matters.
- EMI builds ownership, but investments build financial freedom.
Owning a house doesn't automatically prepare you for retirement, children's education or unexpected expenses. These goals need a separate financial plan.
- Time is your biggest advantage.
Delaying investments until your loan is completely closed means losing valuable years of compounding.
Consider this example:
If you invest ₹5,000 every month for 15 years, assuming an illustrative annualized return of 13%:
- Total investment: ₹9 lakh
- Potential investment value: ₹27.75 lakh
- Illustrative growth: ₹18.75 lakh
Note: This is a mathematical illustration, not an assured return.
- Being debt-free doesn't automatically mean being wealthy.
You may own a debt-free house after 15 years but still have insufficient investments to meet your future financial needs.
Education, healthcare and everyday expenses become more expensive over time. Long-term investments can help you prepare for tomorrow's financial needs.
- Don't depend only on your property.
A house provides security, but it cannot always be converted into cash immediately. A diversified investment portfolio can provide additional financial flexibility.
The takeaway
You don't have to ignore your home loan to start investing. Continue your EMI, maintain emergency savings and consider investing a portion of your surplus alongside loan repayment.
The right balance depends on your loan interest rate, financial goals, risk appetite and investment horizon.
Remember: A debt-free home is an achievement, but a financially independent future is a bigger goal.
Don't spend all your working years paying for today's comfort and forget to invest for tomorrow's dreams.
வீட்டுக் கடன் vs முதலீடு: நீங்கள் செல்வத்தை உருவாக்குகிறீர்களா அல்லது கடனைக் குறைக்கிறீர்களா?
வீடு வாங்குவது என்பது பல குடும்பங்களின் வாழ்நாள் கனவு. இயற்கையாகவே, கடனற்றதாக மாறுவது முன்னுரிமையாகிறது. ஆனால் உங்கள் வீட்டுக் கடனை அடைப்பதில் கவனம் செலுத்தும் அதே வேளையில், உங்கள் எதிர்கால செல்வத்தை கட்டியெழுப்புவதற்கு சமமான முக்கியத்துவம் கொடுக்கிறீர்களா? இது ஏன் முக்கியமானது என்று பார்ப்போம்.
- EMI உரிமையை உருவாக்குகிறது, ஆனால் முதலீடுகள் நிதி சுதந்திரத்தை உருவாக்குகின்றன.
சொந்த வீடு, ஓய்வு, குழந்தைகளின் கல்வி அல்லது எதிர்பாராத செலவுகளுக்கு உங்களைத் தானாகவே தயார்படுத்தாது. இந்த இலக்குகளுக்கு ஒரு தனி நிதித் திட்டம் தேவை.
- நேரம் உங்களின் மிகப்பெரிய நன்மை.
உங்கள் கடன் முழுவதுமாக முடிவடையும் வரை முதலீடுகளை தாமதப்படுத்துவது மதிப்புமிக்க ஆண்டுகளை இழப்பதாகும்.
இந்த உதாரணத்தைக் கவனியுங்கள்:
நீங்கள் 15 ஆண்டுகளுக்கு ஒவ்வொரு மாதமும் ₹5,000 முதலீடு செய்தால், 13% வருடாந்த வருமானம் கிடைக்கும் என்று வைத்துக் கொள்ளுங்கள்:
- மொத்த முதலீடு: ₹9 லட்சம்
- ** சாத்தியமான முதலீட்டு மதிப்பு: ₹27.75 லட்சம்**
- விளக்க வளர்ச்சி: ₹18.75 லட்சம்
குறிப்பு: இது ஒரு கணித விளக்கப்படம், உறுதியான வருவாய் அல்ல.
- கடனில்லாமல் இருப்பது என்பது தானாகவே செல்வந்தராக இருப்பதைக் குறிக்காது.
15 ஆண்டுகளுக்குப் பிறகு நீங்கள் கடன் இல்லாத வீட்டைச் சொந்தமாக வைத்திருக்கலாம், ஆனால் உங்கள் எதிர்கால நிதித் தேவைகளைப் பூர்த்தி செய்ய போதுமான முதலீடுகள் இல்லை.
- பணவீக்கம் காத்திருக்காது.
கல்வி, சுகாதாரம் மற்றும் அன்றாட செலவுகள் காலப்போக்கில் விலை உயர்ந்ததாகிறது. நீண்ட கால முதலீடுகள் நாளைய நிதித் தேவைகளுக்குத் தயாராவதற்கு உதவும்.
- உன் சொத்தை மட்டும் சார்ந்து இருக்காதே.
ஒரு வீடு பாதுகாப்பை வழங்குகிறது, ஆனால் அதை எப்போதும் உடனடியாக பணமாக மாற்ற முடியாது. பன்முகப்படுத்தப்பட்ட முதலீட்டு போர்ட்ஃபோலியோ கூடுதல் நிதி நெகிழ்வுத்தன்மையை வழங்க முடியும்.
எடுக்கப்பட்டது
முதலீட்டைத் தொடங்க உங்கள் வீட்டுக் கடனை நீங்கள் புறக்கணிக்க வேண்டியதில்லை. உங்கள் EMI-ஐத் தொடரவும், அவசரகாலச் சேமிப்பைப் பராமரிக்கவும் மற்றும் உங்கள் உபரியின் ஒரு பகுதியை கடன் திருப்பிச் செலுத்துதலுடன் முதலீடு செய்யவும்.
சரியான இருப்பு உங்கள் கடன் வட்டி விகிதம், நிதி இலக்குகள், இடர் பசி மற்றும் முதலீட்டு அடிவானத்தைப் பொறுத்தது.
நினைவில் கொள்ளுங்கள்: கடன் இல்லாத வீடு என்பது ஒரு சாதனை, ஆனால் நிதி ரீதியாக சுதந்திரமான எதிர்காலம் என்பது ஒரு பெரிய இலக்கு.
உங்களின் அனைத்து வேலை ஆண்டுகளையும் இன்றைய வசதிக்காக செலவழிக்காதீர்கள், நாளைய கனவுகளுக்காக முதலீடு செய்ய மறக்காதீர்கள்.
Read on Muthaleetu Thisai · முதலீட்டு திசையில் படிக்க
Mutual Fund investments are subject to market risks, read all scheme related documents carefully.