Muthaleetu Thisai · முதலீட்டு திசை
Mutual Fund · Murali S · 24 Oct 2026
Why a One-Year FD Now Loses Money in Real Terms for India's Top Taxpayers
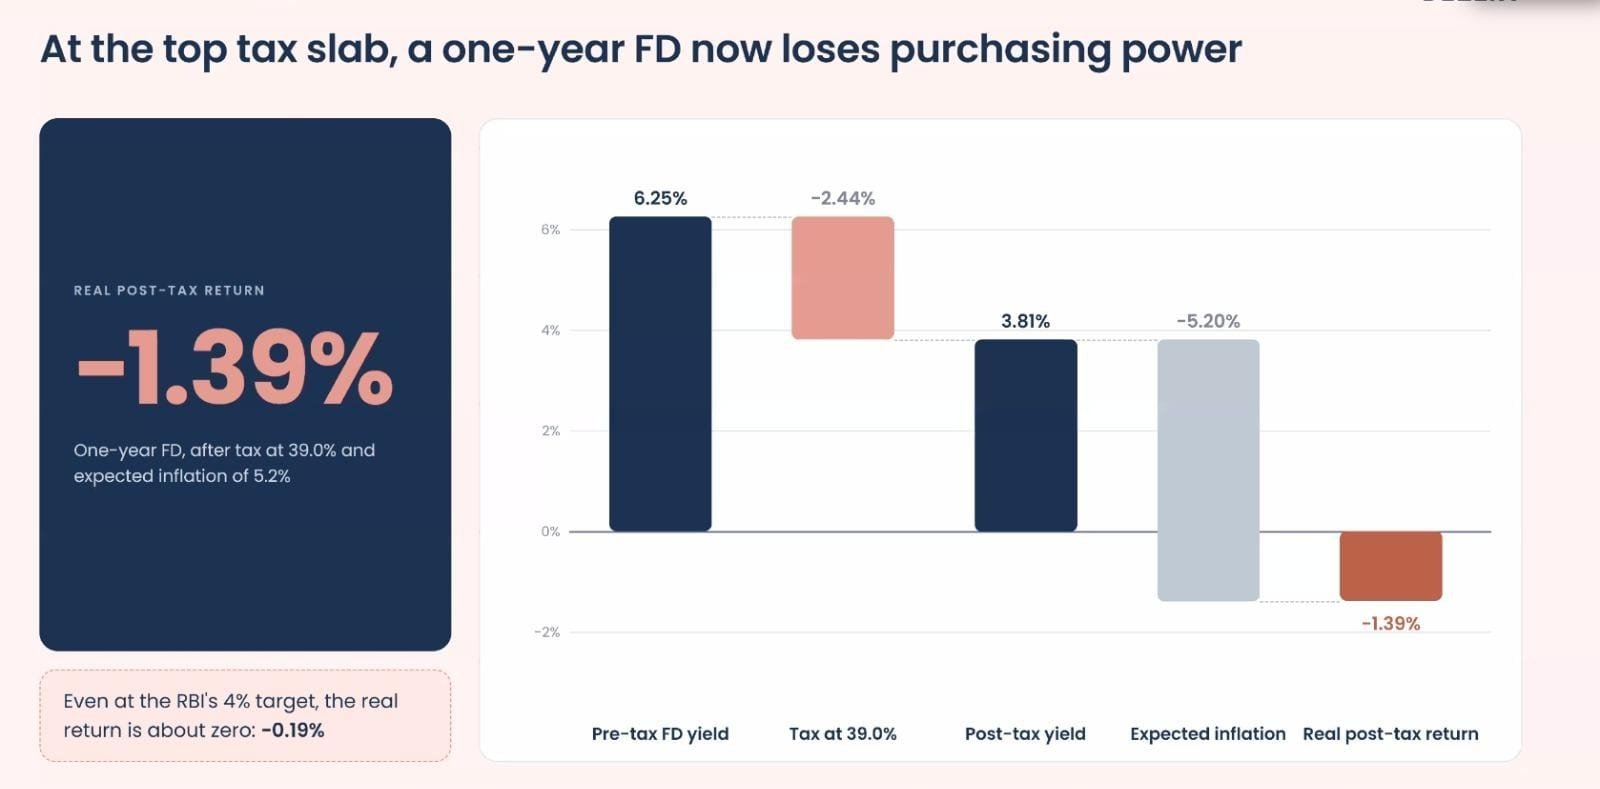
For investors in the highest tax bracket, a one-year fixed deposit no longer protects purchasing power. A 6.25% pre-tax yield shrinks to 3.81% after tax, while expected inflation is 5.2%. The result is a real post-tax return of -1.39%.
Fixed deposits have long been the default safe choice for Indian savers. For those in the top tax slab, that safety is now only nominal.
The math
- Pre-tax yield: A one-year SBI FD offers 6.25%.
- Tax at 39.0%: Under the new tax regime, income above ₹5 crore is taxed at 30%, plus a 25% surcharge and 4% cess, which comes to 39.0%. That takes away 2.44 percentage points.
- Post-tax yield: What remains is 3.81%.
- Inflation: FY27 CPI is projected at 5.2%.
- Real post-tax return: 3.81% minus 5.2% gives -1.39%.
In plain terms, every ₹100 parked in the FD grows to about ₹103.81 after tax, but the cost of living rises by about ₹5.20 over the same year. The investor ends up with less purchasing power than before.
Even the best case doesn't help
If inflation falls to the RBI's 4% target, the real return is still slightly negative at -0.19%. In other words, the FD can at best break even for this investor.
Takeaway
The FD isn't unsafe, since the principal is protected. But for top-slab investors, it works as a capital-preservation tool in name only. High-net-worth savers may want to look at options with better post-tax outcomes, such as tax-efficient debt instruments or equity-linked allocations, based on their risk appetite and with professional advice.
இந்தியாவின் முதன்மையான வரி செலுத்துவோருக்கு ஏன் ஒரு வருட FD இப்போது உண்மையான முறையில் பணத்தை இழக்கிறது
அதிக வரி வரம்பில் உள்ள முதலீட்டாளர்களுக்கு, ஒரு வருட நிலையான வைப்புத்தொகை இனி வாங்கும் திறனைப் பாதுகாக்காது. 6.25% வரிக்கு முந்தைய மகசூல் வரிக்குப் பிறகு 3.81% ஆக சுருங்குகிறது, எதிர்பார்க்கப்படும் பணவீக்கம் 5.2% ஆகும். இதன் விளைவாக உண்மையான வரிக்குப் பிந்தைய வருமானம் -1.39%.
இந்திய சேமிப்பாளர்களுக்கு நிலையான வைப்புத்தொகை நீண்ட காலமாக இயல்புநிலை பாதுகாப்பான தேர்வாக இருந்து வருகிறது. டாப் வரி ஸ்லாப்பில் உள்ளவர்களுக்கு, அந்தப் பாதுகாப்பு இப்போது பெயரளவில் மட்டுமே உள்ளது.
கணிதம்
- வரிக்கு முந்தைய வருவாய்: ஒரு வருட SBI FD 6.25% வழங்குகிறது.
- 39.0% வரி: புதிய வரி ஆட்சியின் கீழ், ₹5 கோடிக்கு மேல் வருமானத்திற்கு 30% வரி விதிக்கப்படும், மேலும் 25% கூடுதல் கட்டணம் மற்றும் 4% செஸ், இது 39.0%. இது 2.44 சதவீத புள்ளிகளை எடுக்கும்.
- வரிக்குப் பிந்தைய வருவாய்: மீதமுள்ளது 3.81%.
- பணவீக்கம்: FY27 CPI 5.2% என கணிக்கப்பட்டுள்ளது.
- உண்மையான வரிக்குப் பிந்தைய வருமானம்: 3.81% கழித்தல் 5.2% -1.39% கொடுக்கிறது.
எளிமையான வகையில், FD இல் நிறுத்தப்படும் ஒவ்வொரு ₹100 வரிக்குப் பிறகு சுமார் ₹103.81 ஆக உயரும், ஆனால் அதே ஆண்டில் வாழ்க்கைச் செலவு சுமார் ₹5.20 அதிகரிக்கிறது. முதலீட்டாளர் முன்பை விட குறைவான வாங்கும் சக்தியுடன் முடிவடைகிறார்.
** சிறந்த வழக்கு கூட உதவாது **
பணவீக்கம் ரிசர்வ் வங்கியின் 4% இலக்குக்குக் குறைந்தால், உண்மையான வருமானம் -0.19% இல் சற்று எதிர்மறையாகவே இருக்கும். வேறு வார்த்தைகளில் கூறுவதானால், இந்த முதலீட்டாளருக்கு FD சிறந்த முறையில் இடையூறு விளைவிக்கும்.
எடுத்துச் செல்லுதல்
முதன்மையானது பாதுகாக்கப்படுவதால், FD பாதுகாப்பற்றது அல்ல. ஆனால் டாப்-ஸ்லாப் முதலீட்டாளர்களுக்கு, இது பெயரளவில் மட்டுமே மூலதன-பாதுகாப்பு கருவியாக செயல்படுகிறது. அதிக நிகர மதிப்புள்ள சேமிப்பாளர்கள் தங்கள் இடர் பசியின் அடிப்படையில் மற்றும் தொழில்முறை ஆலோசனையுடன், வரி-திறமையான கடன் கருவிகள் அல்லது பங்கு-இணைக்கப்பட்ட ஒதுக்கீடுகள் போன்ற சிறந்த வரிக்குப் பிந்தைய விளைவுகளுடன் விருப்பங்களைப் பார்க்க விரும்பலாம்.
Read on Muthaleetu Thisai · முதலீட்டு திசையில் படிக்க
Mutual Fund investments are subject to market risks, read all scheme related documents carefully.